
Creating a balanced portfolio for long-term wealth is a powerful strategy to secure financial stability and growth. A well-structured portfolio minimizes risks while maximizing returns over time. This article explores actionable steps to build a robust investment plan. It draws on data, expert insights, and practical examples to guide readers. Whether new to investing or a seasoned player, these strategies offer clarity and confidence.
Understand Your Financial Goals and Time Horizon
Start by defining clear financial objectives. Are you saving for retirement, a home, or your child’s education? Each goal influences your portfolio’s structure. Short-term goals, like buying a car in three years, demand conservative investments. Long-term goals, such as retirement in 30 years, allow for riskier assets. According to Vanguard, aligning your portfolio with your time horizon reduces volatility risks. Younger investors can lean toward equities for growth. Older investors may prefer bonds for stability. The logic is simple: longer timelines absorb market fluctuations better. Set SMART goals—specific, measurable, achievable, realistic, and time-bound—to shape your strategy. For example, aiming for a 7% annual return over 20 years with options like no credit check loans is precise and trackable.
Assess Your Risk Tolerance
Risk tolerance determines your portfolio’s asset mix. High-risk tolerance suits aggressive portfolios with more stocks. Low-risk tolerance favors bonds and fixed-income assets. A 2023 Investopedia study found that 60% of investors overestimate their risk tolerance. This leads to panic selling during market dips. Use risk assessment tools from platforms like Charles Schwab to gauge your comfort level. Consider your income, net worth, and life stage. A 25-year-old single professional can handle more volatility than a 60-year-old retiree. However, don’t ignore emotional factors. If market swings keep you awake, opt for a conservative mix. Logic dictates that aligning investments with your risk profile prevents costly mistakes.
Diversify Across Asset Classes
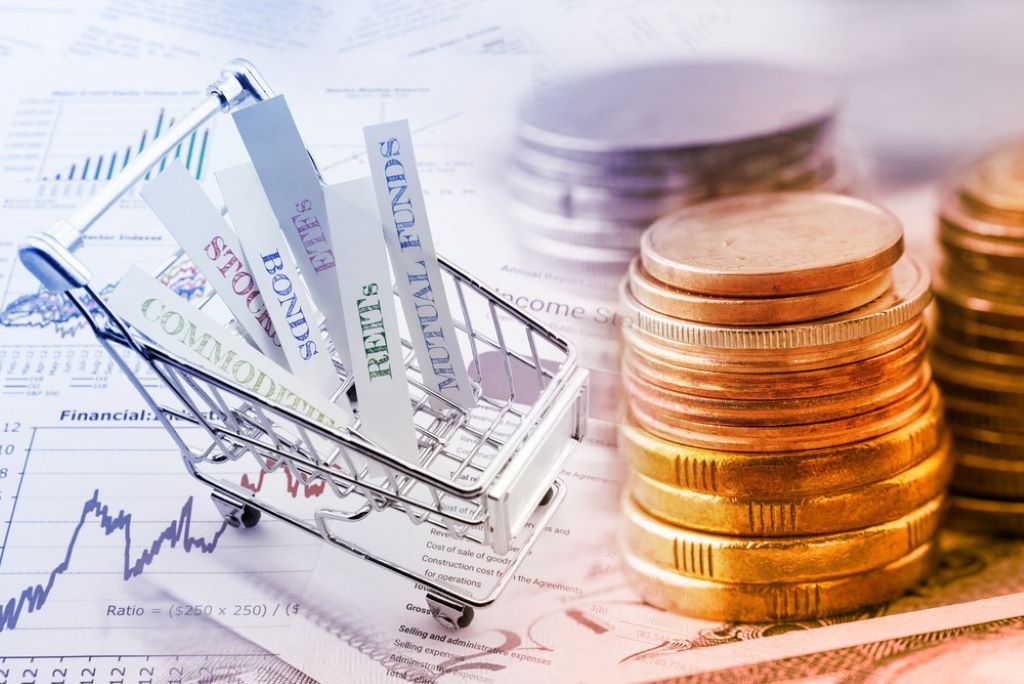
Diversification is the cornerstone of a balanced portfolio. Spreading investments across stocks, bonds, and cash reduces risk. A 2024 Motley Fool report states that diversified portfolios with 60% stocks and 40% bonds saw 22.5% lower annual losses than stock-only portfolios since 1926. Stocks drive growth, bonds provide stability, and cash ensures liquidity. For instance, during the 2008 financial crisis, diversified portfolios recovered faster than equity-heavy ones. Include index funds or ETFs for broad market exposure. Real estate investment trusts (REITs) add another layer of diversification. The logic is clear: no single asset class dominates your returns, protecting against sector-specific downturns.
Allocate Assets Strategically
Asset allocation balances risk and reward. A common rule is the 60/40 split—60% stocks, 40% bonds. However, adjust based on age and goals. The Rule of 110 suggests subtracting your age from 110 to find your stock allocation. A 30-year-old might allocate 80% to stocks and 20% to bonds. A 2024 Vanguard study shows that balanced portfolios with 50/50 splits yielded 6.8% annual returns over 30 years. Allocate within asset classes too. Split stocks between large-cap, small-cap, and international equities. For bonds, mix government and corporate securities. This approach ensures steady growth while cushioning against market swings. Regularly review your allocation to stay aligned with goals.
Incorporate Low-Cost Index Funds and ETFs
Low-cost index funds and ETFs are game-changers for long-term wealth. They offer diversification at minimal costs. A 2025 NerdWallet analysis found that S&P 500 index funds have expense ratios as low as 0.03%, compared to 1% for actively managed funds. Over 30 years, this saves thousands in fees. For example, investing $10,000 in an index fund with a 0.03% fee versus a 1% fee saves $5,000 over 20 years at a 7% return. ETFs like Vanguard’s VTI provide exposure to the entire U.S. stock market. The logic is straightforward: lower fees mean more money compounds over time. Choose funds with proven track records for stability.
Rebalance Your Portfolio Regularly
Over time, market fluctuations skew your asset allocation. Stocks may grow faster, pushing your portfolio to 70% equities. Rebalancing restores your target mix. A 2024 Julius Baer study recommends rebalancing annually or when allocations shift by 5%. For instance, if stocks outperform, sell some and buy bonds to maintain a 60/40 split. This discipline locks in gains and controls risk. During the 2020 market crash, investors who rebalanced avoided overexposure to volatile equities. Use automatic rebalancing tools from robo-advisors like Betterment for efficiency. The logic is undeniable: rebalancing keeps your portfolio aligned with your risk tolerance and goals.
Consider Tax-Efficient Strategies
Taxes can erode long-term wealth. Tax-efficient investing maximizes returns. Municipal bonds offer tax-free income, ideal for high earners. A 2024 Investopedia report notes that municipal bonds save investors in the 37% tax bracket up to 2% annually. Tax-loss harvesting—selling losing investments to offset gains—reduces tax liability. For example, selling a stock at a $5,000 loss offsets $5,000 in gains. Place high-growth assets in tax-advantaged accounts like IRAs. The logic is clear: minimizing taxes leaves more money to grow. Consult a tax advisor to tailor strategies to your situation.
Explore Alternative Investments
Alternative assets like real estate, commodities, or gold enhance diversification. REITs provide real estate exposure without property management. A 2023 Citi Wealth study shows REITs delivered 8% annual returns over 20 years, complementing stocks and bonds. Gold acts as a hedge during economic uncertainty. For instance, during the 2008 recession, gold prices rose 5% while stocks fell 37%. However, limit alternatives to 10-15% of your portfolio. They carry higher risks and fees. The logic is simple: alternatives reduce reliance on traditional markets but require careful selection to avoid volatility.
Leverage Dollar-Cost Averaging
Dollar-cost averaging builds wealth consistently. Invest a fixed amount regularly, regardless of market conditions. A 2024 Voya study found that investors using dollar-cost averaging reduced losses by 15% during volatile markets. For example, investing $500 monthly in an S&P 500 fund buys more shares when prices dip. Over 20 years, this strategy smooths out market highs and lows. Set up automatic contributions through platforms like Fidelity. The logic is compelling: steady investing eliminates the need to time the market, fostering disciplined growth.
Read More:
Monitor and Adjust for Life Changes
Life events like marriage, job changes, or retirement shift your financial needs. Review your portfolio annually or after major events. A 2025 Humboldt Financial study emphasizes that portfolios aligned with life changes outperform static ones by 2% annually. For instance, a new parent may shift to a conservative mix to prioritize stability. Older investors nearing retirement should increase bond allocations. Use financial planning tools from firms like T. Rowe Price to track changes. The logic is evident: adapting your portfolio to life stages ensures it supports your evolving goals.
Seek Professional Guidance
Building a balanced portfolio requires expertise. Financial advisors offer tailored strategies. A 2023 Citizens Bank survey found that advised portfolios outperformed self-managed ones by 3% annually. Robo-advisors like Wealthfront provide low-cost, automated solutions. For complex needs, human advisors excel in tax planning and estate management. For example, a Wealthfront portfolio with a 0.25% fee outperforms self-managed accounts over 10 years. The logic is clear: professional guidance enhances returns while saving time. Choose advisors with fiduciary credentials for trustworthiness.
Stay Disciplined and Patient
Long-term wealth demands discipline. Avoid emotional reactions to market swings. A 2024 Motley Fool study shows that investors who stayed invested during downturns earned 4% higher returns than those who sold. For example, holding through the 2008 crash led to full recovery by 2013. Focus on your goals, not daily market noise. Set automatic investments and rebalancing to stay on track. The logic is undeniable: patience allows compounding to work its magic, building substantial wealth over decades. Also Read: Data-Driven Portfolio Decision-Making Frameworks
Featured Snippet: What Is the Ideal Asset Allocation for a Balanced Portfolio?
The ideal asset allocation for a balanced portfolio depends on age, risk tolerance, and goals. A common approach is the 60/40 split—60% stocks and 40% bonds—for moderate growth and stability. Younger investors may prefer 80% stocks and 20% bonds, per the Rule of 110 (110 minus your age). Older investors might shift to 40% stocks and 60% bonds. Diversify within classes: mix large-cap, small-cap, and international stocks, plus government and corporate bonds. Include 5-10% cash for liquidity. Rebalance annually to maintain your target mix. This strategy, backed by Vanguard’s 2024 data, ensures growth while managing risk effectively.
Professional Tips for Creating a Balanced Portfolio
- Start Small: Begin with low-cost index funds to gain market exposure without high fees.
- Use Tax-Advantaged Accounts: Maximize IRAs or 401(k)s to reduce tax burdens.
- Diversify Globally: Include international stocks to hedge against domestic market downturns.
- Automate Investments: Set up regular contributions to enforce discipline.
- Review Quarterly: Check allocations to catch drifts early.
- Limit Alternatives: Cap alternative investments at 15% to avoid excessive risk.
- Consult Experts: Work with a fiduciary advisor for personalized strategies.
FAQs
-
What is a balanced portfolio?
A balanced portfolio mixes stocks, bonds, and cash to manage risk and growth. It typically follows a 60/40 stock-bond split.
-
How often should I rebalance my portfolio?
Rebalance annually or when allocations shift by 5%, per Julius Baer’s 2024 study, to maintain your target mix.
-
What’s the best way to diversify?
Spread investments across stocks, bonds, REITs, and cash. Use index funds for broad exposure, as Motley Fool suggests.
-
Can I build a portfolio without an advisor?
Yes, use robo-advisors like Betterment or low-cost ETFs. However, advisors boost returns by 3%, per Citizens Bank.
-
How does risk tolerance affect my portfolio?
High risk tolerance allows more stocks; low tolerance favors bonds. Assess via tools like Charles Schwab’s quiz.
-
Are alternative investments necessary?
Not mandatory, but REITs or gold (10-15% allocation) add diversification, per Citi Wealth’s 2023 findings.
-
What’s dollar-cost averaging?
It’s investing a fixed amount regularly to reduce market timing risks, cutting losses by 15%, per Voya’s 2024 study.